

Hi 👋 – E-commerce earnings had a little more spring in their step this quarter. Growth is broadening, companies are investing behind product improvements, and AI is beginning to show up in operating metrics rather than just earnings-call superlatives. In other words, earned growth. Earned growth may be less fun at parties, but it tends to age better.
For more sharp breakdowns of e-commerce, tech, and business models, subscribe below👇
If this helped you think more clearly about e-commerce, send it to a colleague.
Q2 2026 – Growth Broadens
E-commerce is starting to look like itself again. After several years of pandemic distortions, reopening headwinds, inflation pressure, and consumer hand-wringing, the industry appears to be moving back toward its secular growth trajectory.
Encouragingly, success is broadening. Wayfair said the U.S. home category may have finally found a bottom, with flat to slightly positive year-over-year growth for the first time since 2021. Home has been one of the weakest major e-commerce categories since the pandemic normalization began. Etsy, another relative laggard, also saw GMV accelerate. More companies are finding ways to grow again, and the common thread is execution.
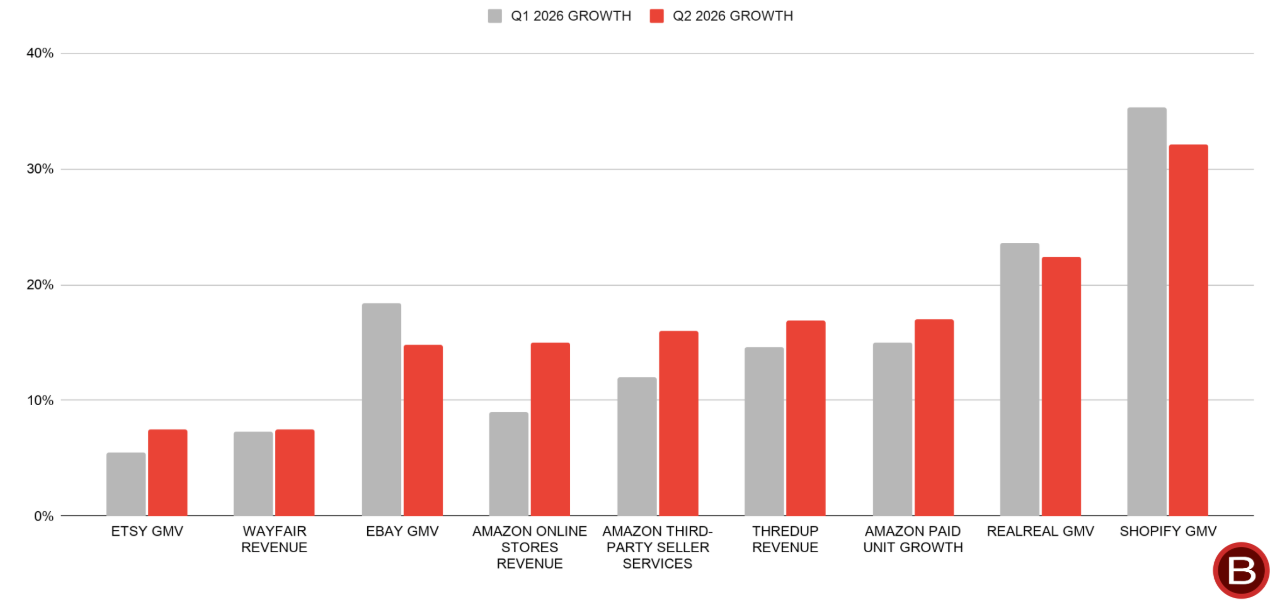
Two companies deserve a special callout here: Amazon for grocery and everyday essentials, and eBay for Focus Categories. They are very different businesses, but their second quarter results tell a similar story. Both are benefiting from strategies that have been years in the making.
For Amazon, the playbook remains simple, but not easy: more selection, lower prices, and faster delivery. One of the company’s key insights is that speed unlocks more orders and expands the TAM. Once Amazon can deliver a broad assortment cheaply and quickly, consumers start considering it for purchases that previously belonged to convenience stores, drugstores, and grocery stores. While it doesn’t take a partner at McKinsey to figure this out, Amazon’s decades of investments in distribution, fulfillment, and logistics give it an unparalleled opportunity to act on the insight1.
Over the years, the company has extended this playbook to more categories. The most recent success stories are groceries and everyday essentials, where the roots trace back to Amazon’s acquisition of Whole Foods Market in 2017. After nearly a decade of iteration and a number of bumps in the road, the company has found the winning recipe, according to CEO Andy Jassy2:
We have finally found something that is a real needle mover for us in offering perishables in our same-day facilities.
(Anyone remember Getir?)
Specifically, same-day baskets containing perishables have triple the units of other same-day orders. It stands to reason that if you are going to have Amazon deliver your peanut butter, you might as well have it deliver your jelly and bread too.
eBay also deserves credit for its Focus Category strategy, which deliberately identified categories where the company has a right to win, then built supply, marketing, trust, and product experiences around enthusiasts in those categories. It tackled them one by one, expanding the number of categories over time. Like Amazon’s grocery push, this strategy has been in progress for years3.
The payoff continued to show up in the numbers. In the second quarter, Focus Category GMV grew 26%, outpacing the rest of the marketplace by roughly twenty percentage points. eBay is winning by becoming a better version of eBay: deeper in the categories where trust and supply density matter the most to enthusiasts.
Neither strategy is complicated. But simple and easy are not the same thing. Everyone can say “selection, price, and speed.” Very few companies can spend years building the infrastructure to make those words matter.
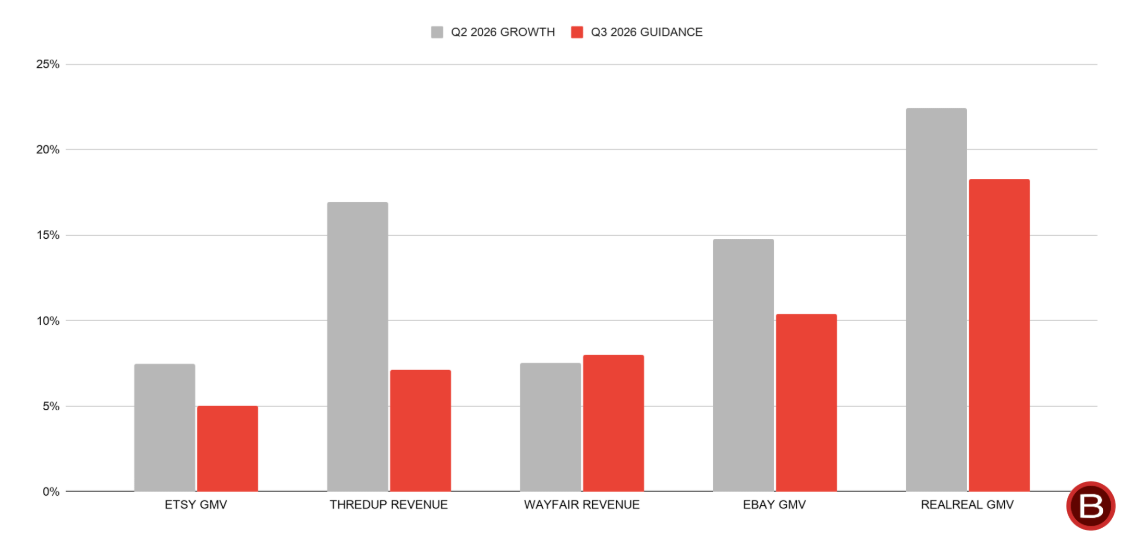
Q3 2026 Guidance – Stable Demand, With One Exception
In general, third quarter guidance pointed to the same basic trend line as the second quarter, suggesting companies are not seeing a major change in conditions. The notable exception was ThredUp, which cut its outlook due to softening trends among lower-income consumers and a more promotional environment.
Consumer & Macro – Healthy, But Selective
Similar to the first quarter, consumer and macro commentary faded into the background in the second quarter. On this front, no news was mostly good news. Consumers are still spending, but they’re not doing so indiscriminately. Companies still need to give them a reason to act: better value, wider selection, increased convenience, a sharper product experience, or some combination of the above.
To the extent there was a macro theme, it was the K-shaped economy. Economists may not be especially good at predicting the next recession or the path of interest rates, but they do know the alphabet.
The starkest example came from ThredUp, which lowered its revenue growth outlook for the year after seeing softness among consumers making $60,000 or less in June. By contrast, trends among customers making $100,000 or more remained healthy. Wayfair underscored the same point, noting that higher-income consumers were outperforming, while its luxury brand Perigold grew more than 35%. At the same time, the company said the mass market remained “very promotional.”
The RealReal reinforced the high-end strength. The company reported its fourth straight quarter of GMV growth above 20%, with sales over $1,000 growing nearly 40%4. That puts The RealReal near the center of a very attractive Venn diagram: affluent consumers on one side, value consciousness on the other. That may be the sweet spot of this market — customers with money, but still a reason to feel smart about the purchase.
In sum, consumers are spending, affluent consumers are spending more freely, and lower-income consumers remain pressured. Nearly everyone, regardless of income, still likes a deal. Two things can be true at once: the consumer can be healthy and value-conscious at the same time.
AI – Disappearing Act
To paraphrase computer scientist Mark Weiser, the best technologies become invisible. They weave themselves into everyday life until we stop noticing them. AI is not quite there yet, but in e-commerce it is starting to work on its disappearing act. The most useful applications are not dramatically new shopping agents. Instead, they are quieter improvements buried inside the buyer or seller experience: search that understands intent, personalization that updates in real-time, listing tools that reduce friction, and product imagery that costs almost nothing.
The second quarter offered both the macro and micro versions of this story.
Let’s start with the macro. Amazon has one of the best windows into market dynamics, and the signal remains strong. AWS revenue grew 37%, its fifth consecutive quarter of acceleration and fastest growth rate in 18 quarters. Amazon also noted that AI is expanding consumption of traditional cloud infrastructure. AI workloads need GPUs, but they also need CPUs, storage, databases, networking, and the rest of the cloud stack5.
Despite strong AWS growth, enterprise AI adoption is still early and uneven. Jassy described the current market as “very barbelled.” On one end are AI labs like Anthropic and OpenAI consuming “gobs and gobs” of compute. On the other are companies using AI for practical cost-saving applications like customer service automation, business-process automation, and fraud detection. The middle ground – AI embedded across existing enterprise workloads – has not yet been built out. Amazon expects that to “change very significantly over time.”
Shopify provides a glimpse of that future. It has meaningful e-commerce market share, a large merchant base, and enough scale to see how AI is affecting commerce. The answer so far is: measurable, but yet not material. Shopify said that AI-driven traffic and orders both tripled year-over-year, though off a small base. Etsy separately noted that about 1% of traffic is coming from LLMs, which suggests low-single-digit AI traffic share is probably a reasonable assumption for scaled e-commerce platforms today.
More interesting is where this AI-driven traffic is going. About 75% of AI-attributed orders came from outside Shopify’s top 100 categories. That suggests AI search may be especially helpful for niche merchants and specific products. Traditional search is good at matching keywords to popular pages. AI is better at interpreting precise intent. Here’s a case study from President Harley Finkelstein on Shopify’s earnings call6:
While search engines rank by popularity against a handful of keywords, AI agents make multiple calls into Shopify’s Catalog working with richer structured data to match products with the buyer’s specific intent rather than just keywords. So when a buyer asks an AI assistant for the best car seat that fits three across a sedan, traditional search focuses on the keyword car seat. An agent, however, understands the actual need, the dimensions, the vehicle type, and the fact that they need three. It searches across all of those constraints at once to find the product that actually works, not just the one that ranks highest. And in this world, relevancy reigns. So specific products made for a specific buyer do particularly well.
If this dynamic holds, AI search could erode some of the discovery advantage of large retailers. By better matching specific intent with specific products, discovery may become less dependent on scale and popularity. The biggest retailer does not necessarily have the best answer to the most specific question. Small merchants could certainly use the help.
That does not mean AI is replacing search. Shopify said traditional search sessions are still growing and account for roughly one-third of storefront sessions.
Shopify is also admittedly AI-pilled. Finkelstein said AI is “baked into how Shopify operates” and that the company has moved from experimentation to rebuilding teams and workflows around what AI can do. ThredUp and Wayfair echoed similar ideas. When Amazon says the middle of the enterprise-AI barbell will eventually fill in, it is effectively betting that more companies will start operating like Shopify.
Moving from the macro to the micro, the AI case studies are getting better. There’s more chicken in the soup than there was a year ago. Every company had a few AI examples, but three stood out.
Wayfair had the clearest cost example. For Perigold, its luxury brand, the company replaced roughly $2 million of traditional lifestyle-imagery production cost with less than $10,000 of AI-enabled imagery production. In the old model, Perigold needed location shoots, travel, photographers, production crews, stylists, and studio time. In the new model, Wayfair uses AI to select products, build rooms, and create photorealistic imagery, with human stylists handling quality control. Unless you are a CFO, this isn’t sexy work, but it is effective. Good things happen when you count pennies.
ThredUp’s example was personalization. The company receives about 250,000 anonymous sessions per day. Historically, logged-out users would not get much personalization until their next visit. Now, ThredUp leverages AI to infer user intent within seconds and changes their product feed in real time. An A/B test for this feature produced a 5% lift in engagement and a 7% increase in profit per new buyer.
Lastly, eBay’s example was supply acquisition. Its Magical Listing tool reduces the effort required for sellers to list items, helping turn idle inventory in consumers’ homes into marketplace supply. As a result, eBay is seeing faster listing times, higher GMV per listing attempt, and measurable increases in the number of C2C sellers and supply.
The thread running through all of this is that AI is becoming more practical and less conspicuous. AI is starting to make existing businesses cheaper, faster, and more relevant. The more it disappears into search, personalization, listings, imagery, and workflows, the more useful it may become.
P&L – Growth, With Guardrails
As growth strengthens, investment is coming back too. Product improvements are becoming an important source of growth, and companies are investing behind them. After the pandemic boom, many companies had to spend several years cleaning up the house after the party: too much hiring, too much fixed cost, too much marketing spend chasing customers who were no longer behaving like it was April 2020. They’re now back to investing, but in a measured way.
Amazon continues to show what this looks like at scale. It is investing behind faster delivery. The judo move is that faster delivery can also lower cost to serve. Shorter shipping distances, fewer package touches, better inventory placement, more units per package, and investments in robotics and automation make its network both faster and cheaper.
eBay is also reinvesting in the areas most tied to its strategy: C2C, Live shopping, shipping, and Depop. The key is that spending is being funded by revenue outperformance. The company is putting money behind the categories and product experiences where it believes it has a right to win, while still guiding to double-digit EPS growth.
AI is helping make this easier. Across the industry, management teams are increasingly talking about AI as a way to do more with the existing organization, reduce the intensity of future headcount growth, and speed up experimentation and product development. The mantra from the post-2022 reset still applies: do more with less.
Etsy was the one exception. Alongside second quarter earnings, the company announced a 12% layoff, primarily in product and engineering. In the modern management dialect, where layoffs are rarely just layoffs, management said the decision was not mainly about cost, but about creating a flatter, faster, more responsive organization. Etsy also plans to backfill many of the impacted roles with machine learning talent to focus on discovery, matching, and personalization.
Investment is coming back, but the adult supervision hasn’t left the room.
C2C Supply – The Battle for the Closet
Another industry trend worth watching is the intensifying battle for C2C supply. eBay, Depop, Poshmark, ThredUp, The RealReal, Vinted, and others are all fighting over the same closets, basements, and garages. eBay noted that C2C GMV grew more than 20% in the quarter, helped by healthy seller and listing growth, and framed the opportunity as unlocking differentiated inventory sitting in consumers’ homes.
That is the right idea. It is also no longer a rare one. C2C supply is attractive because it has built-in circularity: buyers can become sellers, and sellers can become buyers. The RealReal made a similar point, noting that 44% of new consignors in the second quarter were previously buyers, up from 40% two quarters ago. That is the magic of resale marketplaces when they work. The catch is that everyone sees the same magic trick. The winners will be the platforms that make selling feel least like work.
Live Shopping – Not for Soup, Maybe for Sneakers
Live shopping also got a few mentions during earnings calls.. The format has been popular in Asia for years, but has struggled to break into the U.S. mainstream. American consumers, it turns out, have not been eager to recreate QVC inside every app.
Still, the format is showing some momentum. eBay said Live GMV was up roughly eight times year-over-year, albeit off a small base, and Whatnot continues to grow quickly in collectibles and enthusiast categories. Etsy also noted that it is watching the space as it starts to gain traction beyond collectibles.
The format is probably best understood as a new engagement layer for categories where discovery matters. It does not make much sense for toilet paper or Campbell’s Soup. But the combination of entertainment, urgency, community, and scarcity could make it relevant in categories with passionate buyers and unique inventory. That makes it less a replacement for search than a discovery mechanism for the weird, rare, and enthusiast-driven corners of commerce.
In sum, the industry is learning how to grow again without forgetting the belt-tightening lessons of the last few years. E-commerce growth is becoming more earned than automatic. The better operators are growing because they are making commerce cheaper, faster, easier, or more relevant. Consumers are still spending, but selectively, and AI is starting to show up in real metrics rather than just investor-day adjectives. That may not produce the same excitement as 2020, but it is a healthier foundation.
For more sharp breakdowns of e-commerce, tech, and business models, subscribe below👇
If this helped you think more clearly about e-commerce, send it to a colleague.
More Good Reads and Listens
Past quarterly e-commerce reviews from Below the Line: Q1 2026 Back to Growth, Not Back to 2020, Q3 2025 – 2019 Vibes, Q1 2025 – Tariffs, Tai Chi, and T-Shirts, Q4 2024 - A Strong Finish, A Fragile Start, Q3 2024 - Normal-ish, Q2 2024 - A Knife Fight In Mud, Q1 2024 – Keep It Simple, Q3 2023 – Back to Basics, Q2 2023 – Harvest Season, Q1 2023 – Nature is Healing, Q3 2022 – Naughty or Nice? (Part 1), Q3 2022 – Naughty or Nice? (Part 2), Q2 2022 – Slimming Down (Part 1), Q2 2022 – Slimming Down (Part 2), Q1 2022 – An E-commerce Recession (Part 1), Q1 2022 – An E-commerce Recession (Part 2).
Disclosure: The author owns shares of Shopify.

Or as General Omar Bradley – or, depending on the source, General Robert H. Barrow put it, “Amateurs talk about strategy, professionals talk about logistics.”
Amazon, Q2 2026 Earnings Call, July 30, 2026.
The earliest external reference I found was eBay’s Q3 2020 earnings call, though the strategy was likely underway well before it was discussed publicly.
The RealReal’s average order value was about $660 in the second quarter.
Amazon also raised its capex guidance for 2026 to $220 billion from $200 billion, largely due to higher memory costs.
Shopify, Q2 2026 Earnings Call, August 5, 2026.